

IRS Enforcement 2026: What Americans Abroad Should Know
4 min
02-03-2026
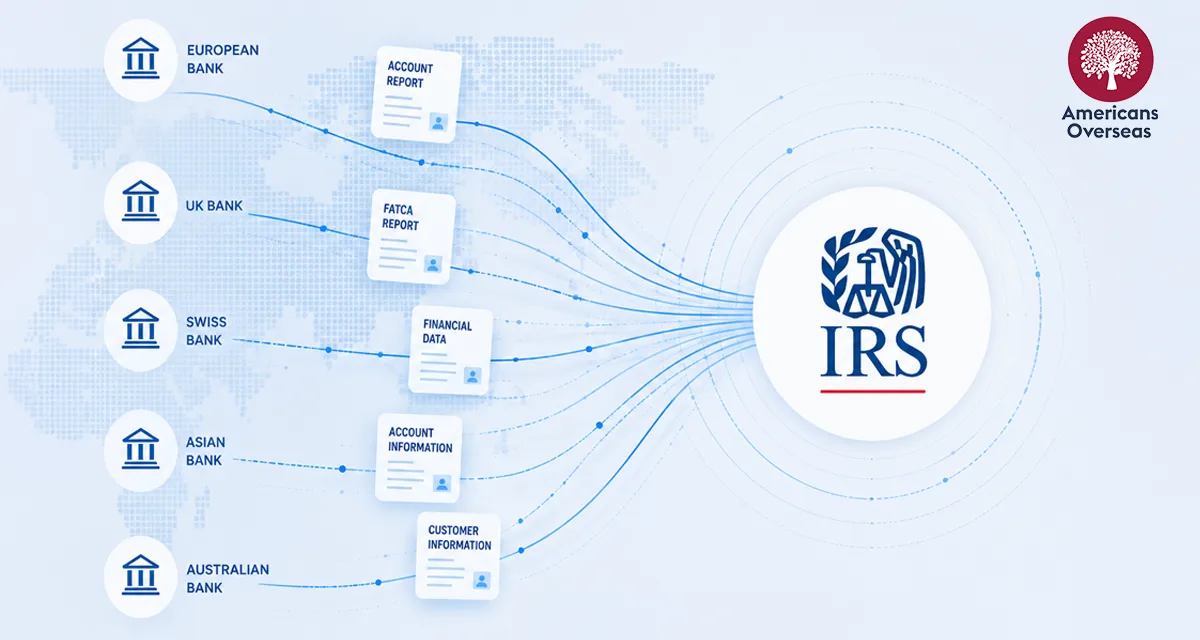
A foreign bank account is increasingly unlikely to remain out of sight. Tax authorities around the world automatically exchange financial information and use it to check tax returns. Developments in 2026 show that this has consequences for account holders. For Americans living abroad, the message is clear: do not assume that the IRS is unaware of your foreign accounts.
International exchanges of bank information mainly operate through two systems. The US system is called FATCA, the Foreign Account Tax Compliance Act. It requires foreign financial institutions to identify and report certain accounts held by US persons, including US citizens. Depending on the country’s FATCA arrangements, financial institutions report the information either directly to the IRS or through their local tax authority.
The other system is CRS, the Common Reporting Standard developed by the Organisation for Economic Co-operation and Development, or OECD. More than 100 countries use it to exchange information about financial accounts held by each other’s tax residents. The United States does not participate in CRS and uses FATCA instead.
Together, FATCA and CRS form a broad international network. The information your tax authority receives depends on the country, the account and the applicable thresholds and exemptions. Simply opening an account across the border does not keep it out of sight.
Argentina shows that FATCA reaches beyond Europe. Its agreement with the United States took effect on January 1, 2023, and the first automatic exchange of information followed in 2024. Argentine financial institutions report certain accounts held by US persons to the IRS through their own tax authority. In return, Argentina receives information about certain US accounts held by its tax residents.
The two countries do not share exactly the same information. The United States provides details of certain interest payments and US-source dividends, for example, but does not report account balances under this agreement. Argentina does report the balance or value of accounts covered by the relevant rules. Even a partial picture can therefore provide a starting point for further checks.
While Argentina illustrates what countries exchange, China shows what can happen next. According to tax advisory firm Rödl, taxpayers have been receiving requests since late 2025 to declare their foreign income. The requests described concern income from 2022 to 2024. Rödl identifies information received through CRS as a likely trigger.
In July 2026, China also published rules for offshore trusts, arrangements in which a trustee holds assets for others. Among other things, gains when assets are transferred into a trust and income generated by the trust can fall within income categories taxed at 20%. More complex offshore wealth structures are therefore also receiving greater tax scrutiny.
Alongside checks, some countries offer an opportunity to correct earlier omissions. On August 16, 2026, India opened a one-time scheme for certain undisclosed foreign assets and income. Eligible taxpayers can submit a declaration by December 31, 2026, under the Foreign Assets of Small Taxpayers Disclosure Scheme, or FAST-DS.
The tax or fee payable differs by category. Asset limits and exclusions apply. A valid declaration and payment can provide protection against further tax, penalties and prosecution under the relevant Indian law. The scheme illustrates that correction may be possible, but always within the conditions set by the country concerned.
In Europe, the debate centers on the privacy conditions under which tax authorities may continue sharing information. A Belgian case has referred questions about FATCA and the General Data Protection Regulation, or GDPR, to the Court of Justice of the European Union.
Spain has put forward proposals to clarify the legal basis for ongoing international exchanges of tax information. On October 21, 2026, the Council of the EU agreed on a negotiating position on the Digital Omnibus, a package of changes to digital rules. The Council wants to clarify that transfers necessary for important reasons of public interest can, under certain conditions, take place repeatedly.
This is not yet a final change in the law, and it does not set aside other privacy safeguards. It does, however, show that governments want information exchange to continue. For background, read our article on FATCA and EU privacy rules.
These examples show how international information exchange works in practice. Countries receive account information, question taxpayers about foreign income and sometimes offer a temporary route to correct omissions. Where the legal basis is challenged, governments are looking for ways to maintain cooperation.
Digital account data also allows tax authorities to compare bank information with tax returns. They do not need to know every transaction to ask further questions: interest, dividends or an account balance may be enough. An account that attracted no questions in the past may therefore receive attention later.
As an American living abroad, you may be affected by both systems. Your bank may report information about your account to the IRS under FATCA, either directly or through the local tax authority. If you are a tax resident of a country participating in CRS and hold an account in another participating country, your country of residence may also receive information about that account.
Unsure whether you have reported everything? Start with a list of your accounts and previous filings, and have any possible gaps assessed. This can help clarify your obligations and any options for correcting omissions. A reporting requirement does not automatically mean that you owe additional US tax.
We, the founders of Americans Overseas, were born in the Netherlands and received our American citizenship through our (American) mother.
When we first learned about the U.S.–Netherlands tax treaty around 2013, we felt disbelief (“this can’t be true”), anger (“how can they do this?”), fear (“will I get fined or have problems?”), and panic (“what should I do?”).
Unfortunately, it is true that there is a U.S. tax obligation for Dutch citizens who acquired American nationality by birth. There was no information from local authorities, the U.S. consulate referred us to the IRS, and the IRS itself was impenetrable.
That is why we started this initiative: to help others with reliable information, to prevent unnecessary panic, and to offer free, no‑obligation assistance. When needed, we can connect you with a network of affordable professionals (accountants) who can help you meet your U.S. tax obligations.
Contact us for more information

General Manager & Partner
Linda Mabelis is the General Manager and Owner at Americans Overseas, dedicated to helping individuals find the right tax attorney for their unique situations. With extensive work experience and a deep understanding of the complexities facing Americans Overseas, Linda is committed to providing personalized and effective solutions.
Read moreUnderstanding the US tax system, the obligations, and all the additional terms can be difficult. Especially if one lives outside of America. Is your question not answered? Contact us.
You cannot assume this for every account. FATCA gives the IRS access to information about certain foreign accounts. What is reported depends on the account and the applicable rules. Thresholds and exemptions apply.
You may. Your bank's FATCA report does not replace an FBAR or Form 8938. Whether you must file these forms depends on your circumstances and their separate conditions and reporting thresholds.
No. Sharing account information, filing forms and paying tax are different matters. Whether you owe US tax depends on your personal circumstances.
You may be able to use an appropriate compliance procedure. Eligibility for the Streamlined Foreign Offshore Procedures includes conditions relating to residence outside the United States and non-willful failures. This route is unavailable if the IRS has already started a civil examination of your returns. Have your circumstances assessed before proceeding.